The property had qualified for the
Regulatory disputes and tax consequences
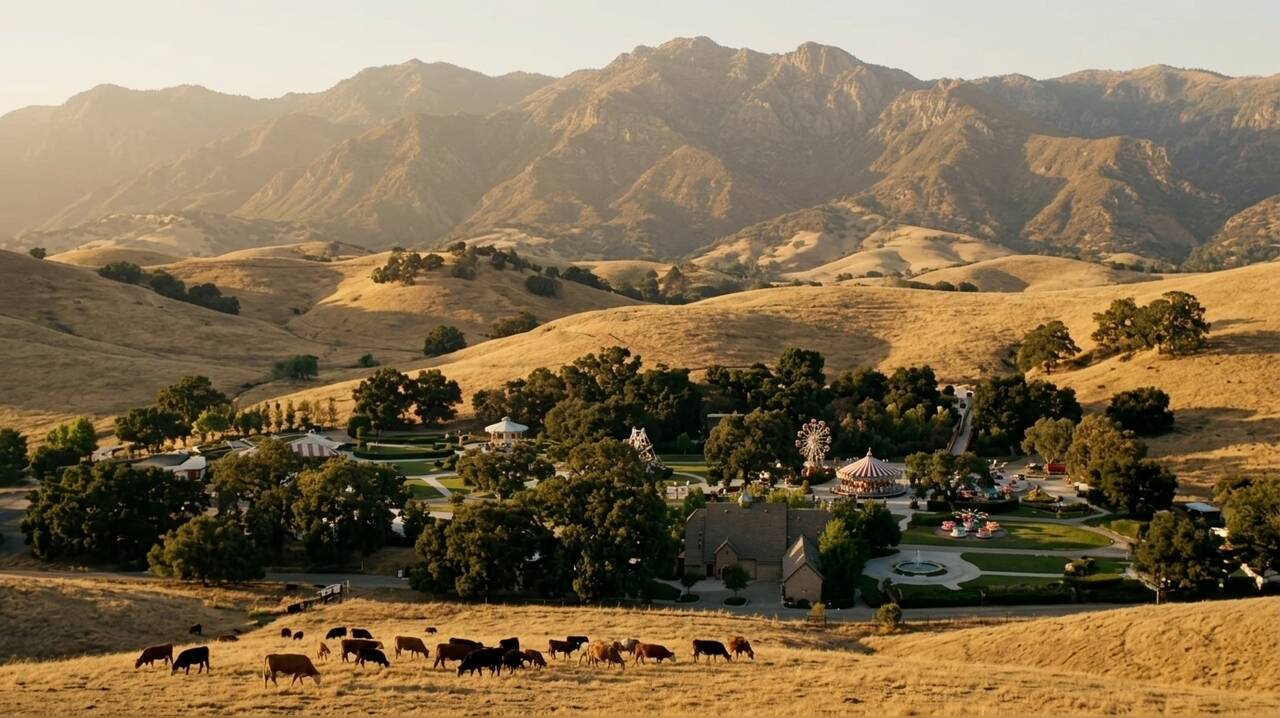
The controversy began when county planners raised concerns regarding the extent of the construction on the property. An investigation by the Santa Barbara County Agricultural Commissioner revealed that numerous developments—including a gatehouse, a primate center, a go-kart track, and a large outdoor movie screen—had been built over the previous decade without proper authorization. While some structures on the ranch had followed standard permit procedures, many of the entertainment-focused additions had not.
In September 2003, the Santa Barbara County Board of Supervisors voted unanimously to remove approximately 70 acres of the estate from the agricultural-preserve program. This decision specifically targeted the areas containing the house, the amusement park, and the zoo, effectively separating these developed sections from the remaining land that continued to qualify for the tax benefit.
Financial impact and program rules
The removal of the 70 acres from the program resulted in a direct financial shift for the estate. County officials estimated that Jackson had been saving approximately $70,000 annually in property taxes through the arrangement. Following the board's decision, the assessed value of the property was expected to rise by roughly $6 million, potentially increasing annual tax liabilities to approximately $200,000.
The increase in taxes was not immediate. Under the provisions of the Williamson Act, land removed from an agricultural contract enters a nine-year non-renewal period, during which the tax assessment gradually adjusts to reflect the property's full value. This phased approach meant that the financial impact of the county's decision would be spread over nearly a decade.
The dispute highlighted the complexities of managing large estates that combine commercial entertainment with agricultural operations. While the Williamson Act provided a legitimate mechanism for tax relief on working ranches, the Neverland case demonstrated the limitations of the program when land use shifts toward intensive, unpermitted development. Following the tax dispute and subsequent financial challenges, the property eventually faced foreclosure in 2008 before being sold and renamed in later years.