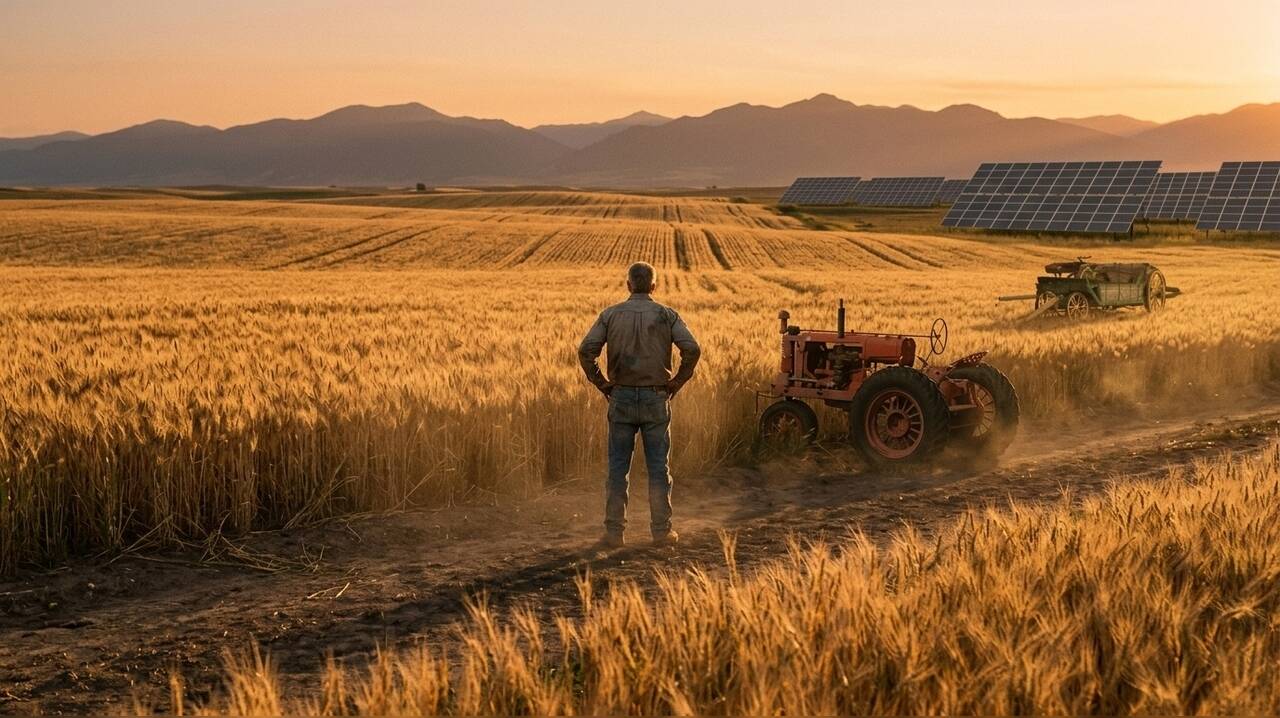
Marc Arnusch, a third-generation farmer in Weld County, Colorado, faced a significant financial crossroads when
The decision to pursue this path proved both complex and costly. To secure the easement, the family invested nearly $1 million in professional documentation, hiring a team of specialists that included tax attorneys, land-use experts, engineers, and geologists. These experts conducted extensive soil testing, boundary surveys, and zoning analyses to determine the property’s “highest and best use,” a standard appraisal metric that accounts for the most financially and legally viable purpose for the land. Based on these professional findings, Arnusch claimed a charitable tax deduction, a mechanism permitted under federal law for qualifying conservation agreements.
IRS Scrutiny and Valuation Disputes
Three years after the deduction was claimed, the Internal Revenue Service initiated an audit of the family’s filing. Arnusch has expressed concerns regarding the process, noting that the auditor assigned to his case appeared to lack specific experience in
This dispute reflects a wider, ongoing conflict between taxpayers and federal regulators over the valuation of conservation easements. Critics of the current IRS enforcement approach argue that the agency frequently produces valuations that are drastically lower than those provided by independent experts. One analysis of ten public cases, conducted by value-analytics specialist Bernie Donachie, found that while taxpayers’ experts valued properties at a collective $358.2 million, IRS assessments for the same land totaled only $1.57 million—a discrepancy of approximately 99 percent.
Shifting Federal Oversight
The IRS maintains that it aims to protect legitimate conservation efforts while simultaneously cracking down on what it characterizes as abusive transactions or inflated tax claims. In a move to centralize its oversight, the agency announced on August 19 the creation of a dedicated Office of Conservation Easements. This new body is tasked with coordinating policy, enforcement, and technical expertise regarding both historic preservation and land conservation.
Simultaneously, the IRS has discontinued its uniform settlement initiative, acknowledging that standardized letters are insufficient to address the diverse nature of individual land cases. For taxpayers currently involved in disputes, this shift does not guarantee a resolution. The agency has indicated that pending cases will continue to be handled through examination or legal representatives, with outcomes determined by individual circumstances and litigation risks.
For Arnusch, the audit represents a personal challenge to his family’s long-term goal of preserving their heritage. Having invested significant resources into the conservation process, he now faces uncertainty regarding the government’s acceptance of his property’s valuation. As the audit proceeds, the family remains focused on the original intent of their decision: protecting the land from development and securing its future as a working farm.